

Under President Donald Trump, the Consumer Finance Protection Bureau (CFPB) has dropped half of all its pending litigation. The result is an impending windfall for the wealthiest of the wealthy, from mega-banks like Capital One that allegedly cheat their customers and automobile companies like Toyota that allegedly used illegal lending practices to companies that want to sell Americans’ private data.
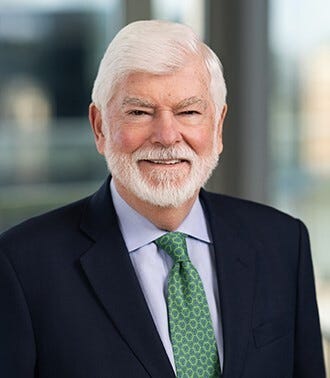
All of this brings to mind the career of Senator Chris Dodd, D-CT, who served five terms from 1981 to 2011. Near the end of that storied legislative career, Dodd was the chief Senate sponsor of the appropriately-named Dodd–Frank Wall Street Reform and Consumer Protection Act. Passed in 2010, the so-called “Dodd-Frank bill” was President Barack Obama’s chief legislative response to the Great Recession that broke out shortly before his first term. In addition to creating the CFPB, the Dodd-Frank bill created the Office of Financial Research, the Financial Stability Oversight Council and the Orderly Liquidation Authority. These organizations have identified future threats to financial stability, empowered the Federal Reserve to regulate supposedly “Too Big To Fail” institutions and facilitate the orderly liquidation of large companies. The Dodd-Frank Act also created the Volcker Rule to restrict banks from speculative investments such as those that triggered the Great Recession in 2007-2008, which came on top of additional regulations on those types of transactions.
“This was a critically-needed bill,” Dodd said. “If we had voted for the $400 billion in infusion from private institutions to stabilize the financial institutions, and then closed the books and said, ‘Problem solved,’ we would've left the structure of our financial services in the same place it was in when the crisis started in 2006, 2007 and 2008.”
Recalling the more than six dozen hearings he held, Dodd said that many of them delved into what caused the economic crisis.
“A lot of it related, obviously, to the fact that mortgages were not being carefully selected,” Dodd said. “We were encouraging people to take on financial obligations they couldn't afford at all. And so there was all of that background as well that led to the decision to go forward with a bill.”
Anticapitalist scholars like the University of Massachusetts Amherst economist Dr. Richard Wolff criticize regulations like the Dodd-Frank Act for being too modest. They argue that, by leaving these mega-banks in place at all, these regulations fail to root out the underlying causes of catastrophes like the Great Recession. By contrast, Trump seems to aspire to have virtually no effective regulations on these big businesses — not just mega-banks, but any business large enough to hurt the American public.
This brings us back to the CFPB.
“What's happening lately, and I cite one example, is the Consumer Financial Protection Bureau,” Dodd said. “I was determined to include that as part of the bill because it was long overdue. If a consumer got into trouble with a bank, and particularly when it was the bank's fault or the lending institution's fault, you had to go to court, you had to get a lawyer and you had to bring a lawsuit, which was almost impossible, particularly for many people who were in trouble financially.”
Many of the people who most needed assistance couldn’t afford it under the status quo, Dodd recalled. This is one area being targeted by Trump.
“You could hardly afford private legal services,” Dodd said. “There were pro bono firms that did that work for them, but only on a relatively small scale. So we have watched now in the last little more than a hundred days are efforts to destroy the funding mechanism for the Consumer Financial Protection Bureau.” Even though it has returned “over $20 billion in resources to consumers since the enactment of the bill,” Trump and his administration insist it must be done away with.
“That is, of course, just to destroy the ability of consumers, individually and generally, to have the kind of protections that they deserve to have, particularly people who live paycheck to paycheck trying to survive,” Dodd said. After reviewing his progress protecting consumers from credit card companies and predatory real estate agents, he now worries that one cornerstone of this progressive legacy will soon be removed.
“The CFPB and the financial reform bill, the Dodd-Frank bill, was a major legislative achievement and more importantly, a major substantive achievement,” Dodd said. “Today, we're watching an administration try to make it all go away and get rid of all the effort we put in to creating that kind of protections that have made a difference to consumers.”
Only time will tell if Trump succeeds. If he does, though, Americans may soon revert to the pre-2010 conditions that Dodd worked so hard — and so successfully — to keep in our collective past.
Back Seat Socialism
Column by Matthew Rozsa who is a professional journalist for more than 13 years. Currently he is writing a book for Beacon Press, "Neurosocialism," which argues that autistic people like the author struggle under capitalism, and explains how neurosocialism - the distinct anticapitalist perspective one develops by living as a neurodiverse individual - can be an important organizing principle for the left.
Twitter (X) @MatthewWRozsa
Maybe we should stop being “consumers”. And shut the whole fucking thing down. Start being people again.